What Is a Global Capability Center (GCC)? A Complete Guide for 2026
7 PM tools ranked for professional services. Features, comparison table, and verdict.
Date Posted:
October 1, 2026
Share This:
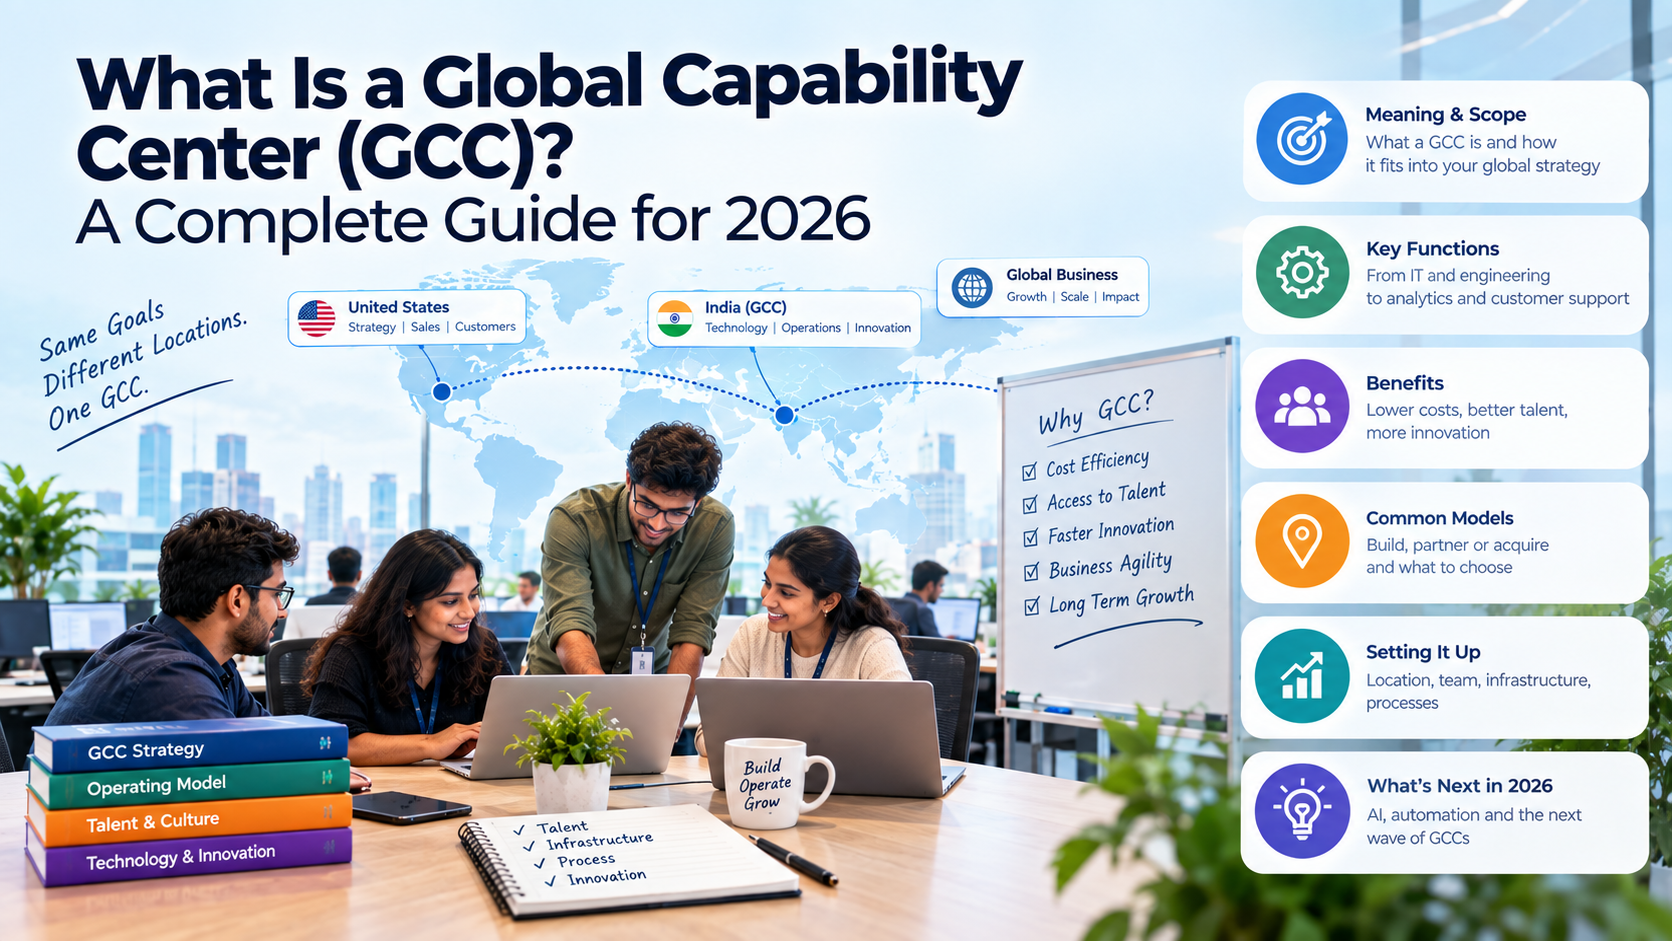
What Is a Global Capability Center (GCC)? A Complete Guide for 2026
Global Capability Centers have moved from a footnote in offshore strategy to the dominant model for how multinational enterprises build and operate technology, analytics, and professional services capability at scale. In 2026, India alone hosts more than 1,700 GCCs employing over 1.9 million professionals. Fortune 500 companies, European mid-market enterprises, and fast-growing technology firms are all building GCCs at a pace that shows no sign of slowing. This guide explains what a GCC is, how it differs from traditional outsourcing, why India has become the world's GCC capital, and what it takes to run one as a genuine value center rather than a cost reduction exercise.
A Global Capability Center (GCC) is a captive delivery center owned and operated by a multinational enterprise in a lower-cost geography, typically India, to deliver technology, analytics, finance, operations, or professional services functions for the parent organization or its clients. Unlike outsourcing, a GCC is wholly owned by the enterprise: the people are employees, the IP is owned internally, and the delivery capability is a strategic asset rather than a vendor relationship.
What Is a Global Capability Center?
A Global Capability Center (GCC), also called a Global In-house Center (GIC) or Captive Center, is a subsidiary or wholly owned unit of a multinational enterprise established in a specific geography to deliver defined business functions. The defining characteristic is ownership: unlike a third-party outsourcing arrangement, a GCC is part of the parent enterprise. Its employees are the enterprise's employees, its infrastructure is the enterprise's infrastructure, and the capability it develops belongs to the enterprise permanently.
The functions delivered through GCCs have expanded dramatically over the past decade. Early GCCs were primarily back-office and IT support centers. Modern GCCs in 2026 run product development, AI and machine learning research, financial planning and analysis, legal operations, cybersecurity, customer experience, and increasingly, professional services delivery for the parent organization's external clients.
A GCC is not a cheaper version of outsourcing. It is a different strategic choice: trading vendor flexibility for ownership of capability, IP, and talent at global cost structures.
GCC vs Outsourcing: The Strategic Difference
| Dimension | GCC (Captive) | Outsourcing (Third-Party) |
|---|---|---|
| Ownership | Wholly owned by the enterprise | Vendor-owned; enterprise is a client |
| IP and data | All IP remains with the enterprise | IP ownership governed by contract; data shared with vendor |
| Talent | Enterprise employees; enterprise culture and career path | Vendor employees; divided loyalty, higher attrition |
| Control | Full operational control over processes, tools, priorities | Governance via SLAs; limited operational visibility |
| Setup cost | Higher upfront: entity setup, recruitment, infrastructure | Lower upfront: vendor absorbs setup and staffing cost |
| Ongoing cost | Lower per-FTE long term; no vendor margin | Higher per-FTE; vendor margin built into rates |
| Strategic depth | Builds enterprise-grade capability and institutional knowledge | Transactional; capability leaves with the contract |
| Flexibility | Harder to scale down quickly | Easier to exit; ramp down with contract notice |
| Best for | Core functions, IP-sensitive work, long-term capability building | Non-core functions, variable demand, commodity work |
Why India Dominates Global GCC Establishment
India produces approximately 1.5 million engineering graduates per year, the largest pipeline of technology talent in the world. The quality distribution spans from entry-level developers to world-class AI researchers, machine learning engineers, and domain-specialist analysts.
Fully loaded employee cost for a senior software engineer in India is approximately 20 to 30% of the equivalent cost in the US or Western Europe. For a 200-person GCC, this differential represents $15M to $25M in annual labor cost savings at equivalent skill levels.
India is the world's largest English-speaking professional workforce. Combined with decades of experience working in globally distributed teams, Indian GCC employees integrate into global organizations with significantly lower friction than GCC talent pools in most other geographies.
Bangalore, Hyderabad, Pune, Chennai, Mumbai, and Gurugram offer world-class office infrastructure, reliable connectivity, professional services ecosystems (legal, accounting, payroll), and established GCC communities with shared best practices.
India has a well-established legal framework for subsidiary entity formation, IP protection, data privacy compliance, and cross-border fund repatriation. The SEZ (Special Economic Zone) framework provides additional tax incentives for qualifying GCCs.
The density of existing GCCs in India has created an ecosystem of vendors, consultants, real estate providers, and talent networks specifically designed to support GCC establishment and operation, reducing the friction of setup for new entrants significantly.
What Functions Modern GCCs Deliver in 2026
The scope of GCC functions has expanded dramatically from the IT support and back-office processing origins of the early 2000s. In 2026, the most common GCC function categories are:
| Function Category | What It Covers | Typical GCC Maturity |
|---|---|---|
| Technology and Engineering | Software development, product engineering, QA, DevOps, cloud infrastructure, cybersecurity | Most established; many GCCs are strategic technology centers |
| Data and Analytics | Business intelligence, data engineering, AI/ML research, predictive modeling, reporting | Fast growing; highest value-add perception in 2026 |
| Finance and Accounting | FP&A, treasury operations, tax compliance, accounts payable/receivable, financial reporting | Mature; strong ROI from standardization and automation |
| Professional Services Delivery | Consulting delivery, managed services, client engagement support, project management | Emerging; highest complexity, requires PSA-grade operations |
| Legal and Compliance | Contract management, regulatory compliance, legal research, IP management | Growing; driven by legal cost reduction pressure |
| Customer Experience | Customer success, technical support, implementation support, account management | Large scale; shifting from cost-focused to value-focused |
| HR and Talent Operations | Recruitment, L&D, HRBP functions, compensation analysis, people analytics | Moderate; often one of the first functions moved to GCC |
The Evolution from Cost Center to Value Center
The narrative around GCCs has shifted fundamentally over the past five years. The early GCC model was unambiguously cost-driven: establish a center in India, hire at Indian wage rates, reduce headcount in the parent market, and capture the labor arbitrage. This model still exists and still drives significant GCC establishment activity. But the leading GCCs in 2026 are not cost centers. They are capability centers that generate strategic value far beyond labor cost reduction.
BPO-style back-office processing and IT support. Primary metric: headcount cost reduction vs. onshore equivalent. Minimal strategic contribution; transactional in nature.
Standardized processes, quality management, and continuous improvement. GCCs begin owning end-to-end processes rather than just executing tasks. Metrics expand to include quality, cycle time, and error rates.
GCCs run product development, AI research, and platform engineering. Begin generating IP rather than just executing instructions. Talent profile shifts significantly upward; GCC leads hold global roles.
GCCs operate as P&L-accountable business units delivering services to internal clients and increasingly to external clients. AI agents augment delivery teams. GCC leadership sets global strategy. The GCC is a competitive advantage, not a cost line item.
Who Is Setting Up GCCs in 2026
GCC establishment is no longer the exclusive domain of Fortune 500 companies. The ecosystem has matured to the point where mid-market enterprises with 500 to 5,000 employees globally are establishing GCCs in India, often starting with 20 to 50 people and scaling rapidly. The major growth segments in 2026 are:
The largest GCC segment by headcount. US and European banks, insurance companies, and asset managers running technology, analytics, compliance, and operations functions from India GCCs. Key growth driver: regulatory technology and AI risk management.
US and European software companies running engineering, product, QA, and customer success from India GCCs. The fastest-growing segment; many mid-market SaaS companies are establishing their first India engineering presence as a GCC rather than through outsourcing.
Pharma, medtech, and healthcare services companies running clinical data management, regulatory affairs support, and technology functions. Growing significantly on the back of AI-driven drug discovery and clinical trial management needs.
US and European industrial companies establishing GCCs for engineering design, supply chain analytics, and ERP operations support. Driven by Industry 4.0 digital transformation programs that require sustained engineering capability at global cost structures.
Operating Challenges Every GCC Leader Faces
| Challenge | Why It Happens | How Leading GCCs Address It |
|---|---|---|
| Talent attrition | India IT talent market is highly competitive; lateral movement is the norm | Structured career paths, global role access, above-market compensation, ESOP programs |
| Parent organization integration | GCC perceived as offshore execution unit rather than strategic partner | GCC leadership in global strategy forums; GCC-owned global programs; shared OKRs |
| Utilization visibility | Parent has limited visibility into GCC resource deployment and capacity | Connected PSA platform that surfaces GCC utilization to global leadership in real time |
| Billing and chargeback complexity | Intercompany billing, transfer pricing, and multi-currency settlement require structured processes | PSA with multi-entity billing and INR/USD settlement automation |
| Time zone coordination | India-US overlap is limited (1.5 to 4 hours depending on US timezone) | Structured handover protocols, async-first communication, overlap optimization |
| Compliance and regulatory | Indian labor law, GST, FEMA, and transfer pricing regulations require ongoing legal and finance attention | Dedicated India compliance function; Big 4 or specialized India counsel |
How GCCs Are Measured in 2026
The metrics used to evaluate GCC performance have evolved alongside the GCC model itself. Cost-only metrics are insufficient for Generation 3 and 4 GCCs. The leading measurement frameworks use a balanced scorecard that captures cost efficiency, delivery quality, capability development, and strategic contribution simultaneously.
Cost per FTE vs. onshore equivalent, total GCC operating cost vs. budget, cost per unit of output by function, and savings delivered vs. pre-GCC baseline. Still important but no longer sufficient as the only measurement dimension.
SLA attainment by function, defect rates, rework percentage, on-time delivery rate, and client satisfaction scores (for GCCs serving internal clients with defined service levels). Quality metrics are the first line of defense against GCC value perception erosion.
Attrition rate, time to hire, bench strength, skills coverage vs. target taxonomy, and percentage of employees in senior or global roles. Talent metrics predict GCC future capability and cost stability better than any other leading indicator.
IP generated, patents filed, global programs led from the GCC, and business value delivered beyond the contracted scope. These are the metrics that distinguish a cost center GCC from a capability center GCC and justify continued investment in GCC capability building.
KEBS is designed for the GCC operating model at every layer. Resource management handles skills-based allocation across the GCC talent pool, with bench visibility, demand forecasting, and AI-driven staffing recommendations that reflect the GCC's specific skills taxonomy. Multi-entity billing and INR/USD settlement automation handles intercompany chargeback to the parent organization without manual reconciliation. Time zone-aware scheduling and reporting surfaces GCC utilization to global leadership in real time rather than through periodic manual reports.
KAIS (KEBS AI Suite) is particularly relevant for GCC operations: KII monitors GCC-wide utilization and bench patterns across every practice and function, surfacing risk before it becomes a capacity crisis. KIR recommends specific resource-to-project matches from the GCC talent pool based on skills, availability, and cost structure. KIA automates intercompany billing triggers, generates utilization reports for parent organization governance, and produces the three-year capacity forecast that GCC leadership needs for hiring and infrastructure planning.
Customers including Maveric Systems, Zifo Technologies, Mindsprint, and Agilisium, all of whom operate GCC-adjacent delivery models, use KEBS to run their operations with the same discipline and visibility that leading GCCs apply to their internal capability centers. For US enterprises setting up India GCCs, KEBS provides the operational infrastructure to move from cost-center reporting to genuine P&L accountability from day one.
Frequently Asked Questions
Running a GCC? KEBS Provides the Operational Infrastructure to Make It a Profit Center.
Skills-based resource management, multi-entity billing, INR/USD settlement, real-time utilization visibility, and KAIS AI forecasting, built specifically for GCC and IT/ITeS delivery models. Rated 4.7/5 on G2.
Book a Free Demo →